Buying a home doesn't end with just having a subscription savings account. There are several stages — checking your eligibility, applying for a subscription, and working out your financing — laid out here in order.
1If you're young, start with a preferential-rate subscription savings account
If you're a homeless young person aged 19 to 34, it's to your advantage to open a Youth Housing Dream Subscription Savings Account, which gives you a preferential interest rate. If you later win a subscription, it leads into the low-interest Housing Dream Loan.
2If you're ready to apply for a subscription
For private apartment/officetel subscriptions, Cheongyak Home handles everything from checking eligibility to applying and announcing winners. If you're interested in public rental or pre-sale housing (Happy Housing, National Rental Housing, and the like), you'll need to check separately on LH Apply Plus.
3If you're short on funds, check policy loans first
Before looking into a commercial bank loan, the right order is to first check on the Housing and Urban Fund e-Deun-deun whether you qualify for a low-income policy loan such as the Didimdol home-purchase loan or the Beotimmok jeonse loan. These often carry a lower interest rate than commercial banks.
4If your income is low, also check housing-welfare benefits
If a subscription or purchase still feels like too much of a stretch, you can first look on the My Home Portal for housing-welfare benefits — such as public rental housing or housing benefit — that fit your income and asset level. The property register and actual-transaction-price checks you should do right before signing a contract are covered separately in the "What to check before signing a jeonse lease" guide.
Services mentioned in this guide
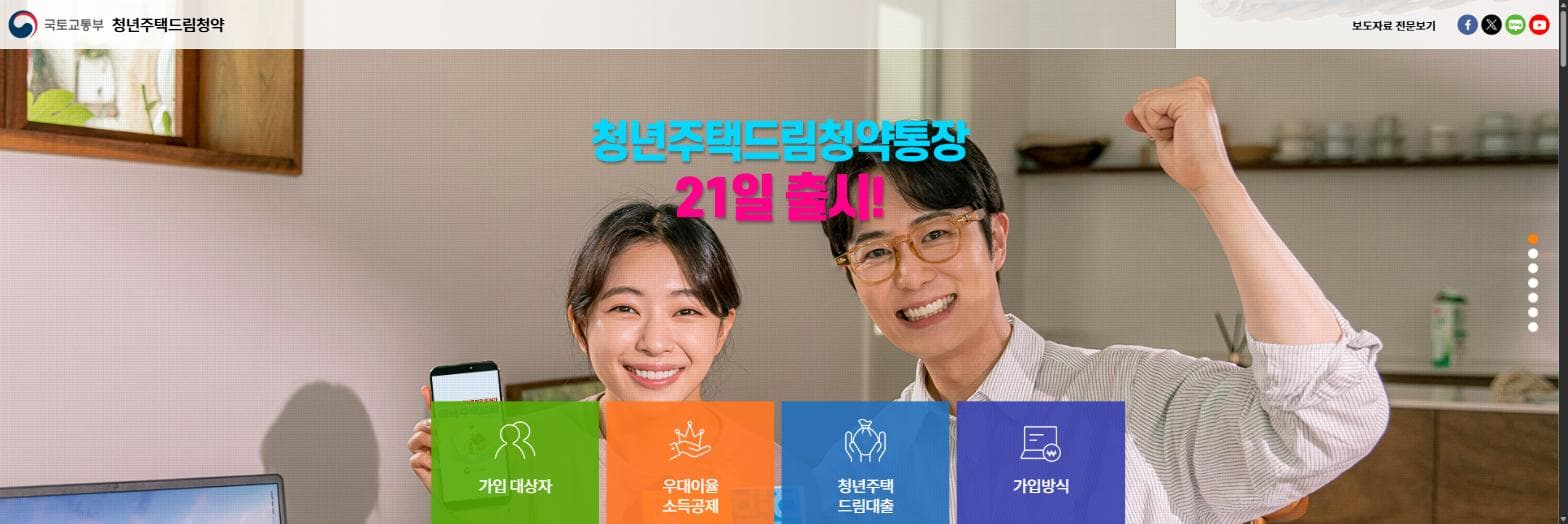
Youth Housing Dream Subscription Savings Account
A preferential-rate subscription savings account that helps homeless young people aged 19-34 save toward a home, with subscription winners eligible for the low-interest Housing Dream Loan - a Ministry of Land, Infrastructure and Transport product
24 hours (account opening during participating banks' business hours)
Operated by · 국토교통부
Cost · Free
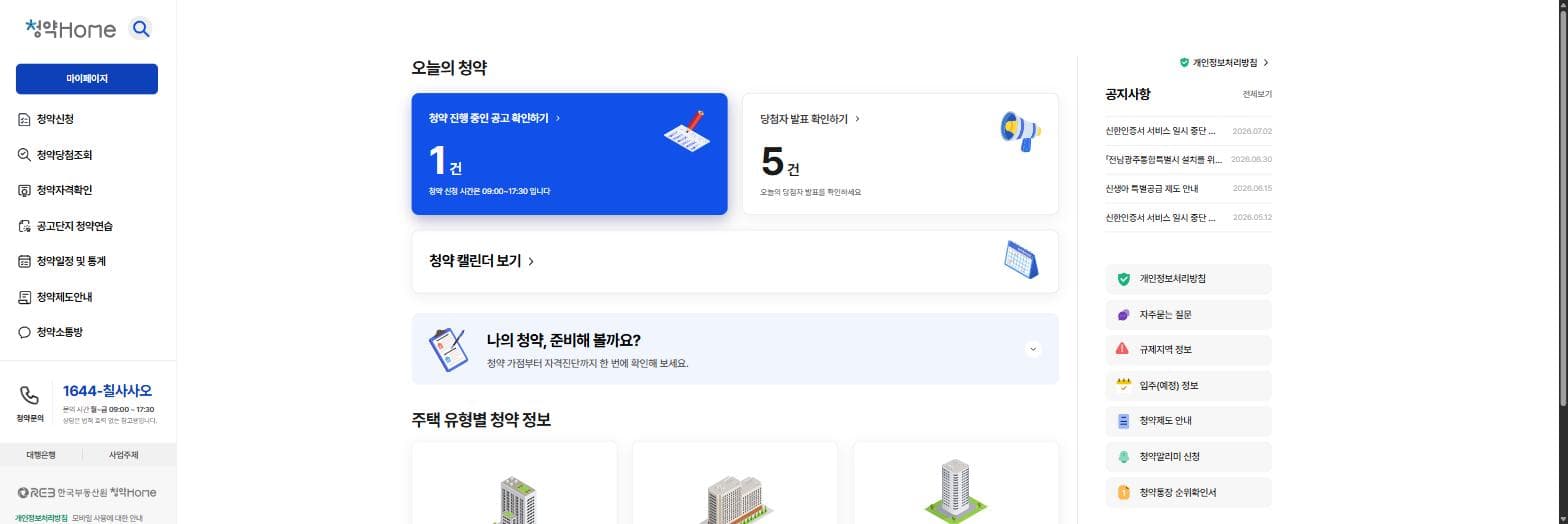
Cheongyak Home
Korea Real Estate Board's official subscription portal handling everything from applying for apartment/officetel subscriptions to checking eligibility and announcing winners
Online anytime; customer center weekdays 09:00-17:30
Operated by · 한국부동산원
Cost · Free
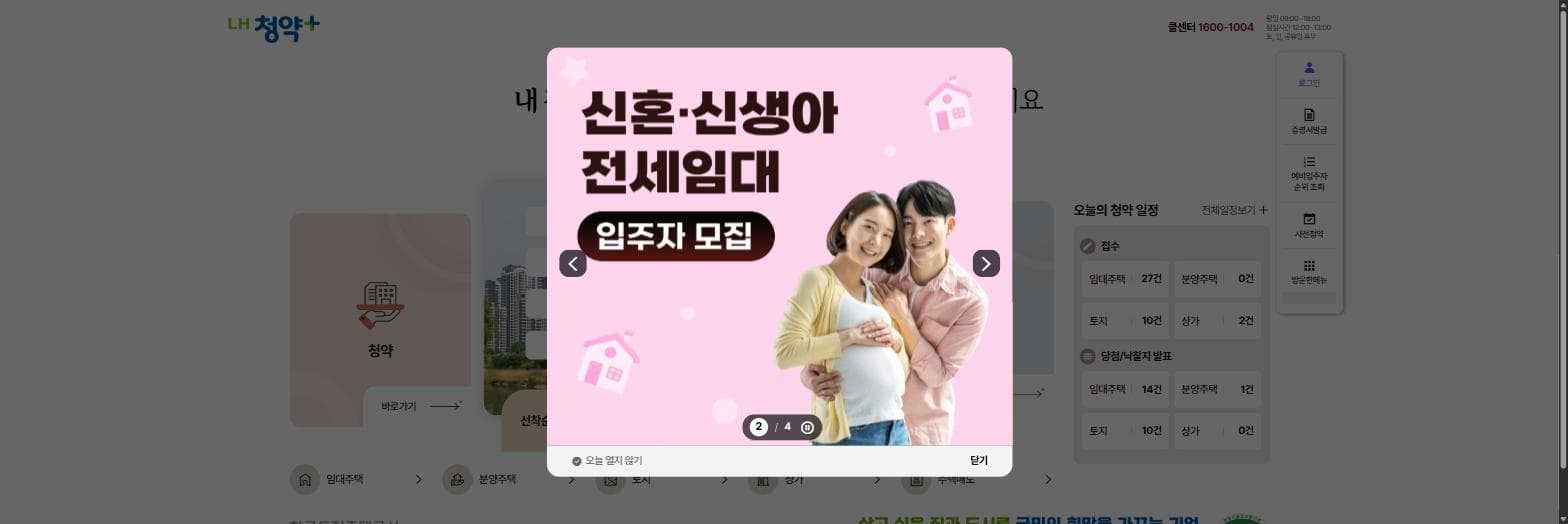
LH Apply Plus
LH's (Korea Land and Housing Corporation) official portal for checking and applying online for public rental/pre-sale housing subscriptions such as Happy Housing and National Rental Housing
24 hours (call center 1600-1004)
Operated by · 한국토지주택공사(LH)
Cost · Free
Housing and Urban Fund e-Deun-deun
A Ministry of Land, Infrastructure and Transport official system for applying online, without visiting a bank, for low-income housing loans such as the Didimdol home-purchase loan and Beotimmok jeonse loan
24 hours (call center weekdays 09:00-18:00)
Operated by · 국토교통부
Cost · Paid
My Home Portal
An integrated portal that finds the public-housing and welfare benefits - such as public rental housing and housing benefit - that fit your income and asset level in one place
24 hours (call center 1600-1004)
Operated by · 국토교통부·한국토지주택공사
Cost · Free