When debt becomes unmanageable, the hardest part is often just not knowing who to call. Before you get tempted by private-lender ads, here is the order of public channels that can actually help, organized by situation.
1If you're not delinquent yet, but need emergency living expenses
If your credit score is too low for a bank loan but you're not yet delinquent, start by checking policy-backed low-income financial products from the Korea Inclusive Finance Agency, such as Sunshine Loan and Miso Finance. Check whether you qualify before resorting to a private lender.
2If you owe debt to multiple places and repayment is already overwhelming
If you are struggling to repay debt owed to several financial companies on schedule, get debt-adjustment counseling from the Credit Counseling and Recovery Service. If you are not yet delinquent, or delinquent 30 days or less, you qualify for Fast-Track Debt Adjustment; 31–89 days gets Pre-Workout (pre-workout debt adjustment); 90 days or more gets Individual Workout. The interest reduction and repayment period vary depending on how long you have been delinquent, and Individual Workout onward also allows partial principal forgiveness. It is a public process handled without litigation, and a single phone call (1600-5500) is enough to be guided to the program that fits your delinquency status.
Individual Workout offers especially large reductions. Depending on your repayment capacity, you can have up to 70% of principal forgiven (up to 90% for socially vulnerable groups), and repay unsecured debt over as long as 10 years, or secured debt over as long as 35 years. Debt collection stops starting the day after you apply, so if you are currently being hounded by collectors, simply applying for counseling can put out the immediate fire.
3If you don't even know where to start looking
If you cannot tell whether you need policy funding, debt adjustment, or personal rehabilitation, you can just call the Regional Financial Welfare Center (Financial Welfare Call Center 1397) first. Run by the Korea Inclusive Finance Agency, it guides you through everything from policy-fund counseling like Miso Finance and Sunshine Loan, to Credit Counseling and Recovery Service debt adjustment, to referrals for personal rehabilitation and bankruptcy, all in one call.
4If you have no income or your debt is too large even for adjustment
If your debt is too large to resolve even through Credit Counseling and Recovery Service adjustment, or you have no income at all, you will need to look into personal rehabilitation or bankruptcy through the courts. These procedures are often difficult to handle without a lawyer, but if your income is low, the Korea Legal Aid Corporation can help you prepare documents and file for free.
5To sum up the order
- Not delinquent yet, need emergency cash → check policy funding at the Korea Inclusive Finance Agency first
- Already delinquent on multiple debts → get debt-adjustment counseling from the Credit Counseling and Recovery Service
- Too severe even for adjustment → personal rehabilitation/bankruptcy counseling through the Korea Legal Aid Corporation
If you don't know where to begin, it is fine to just start by calling the Credit Counseling and Recovery Service for counseling — they will direct you to whichever agency actually fits your situation during the call. Be careful of private companies that contact you first saying "we'll help sort out your debt," or anyone demanding a fee — those are not public agencies.
Services mentioned in this guide
Korea Inclusive Finance Agency
An agency that guides low-income people who struggle to get mainstream loans toward policy microfinance products like Sunshine Loan and Miso Finance, and debt-adjustment counseling
Weekdays 09:00–18:00 (online consultation booking anytime)
Operated by · 서민금융진흥원
Cost · Free
Credit Counseling and Recovery Service (1600-5500)
A public debt-adjustment body where people struggling to repay debt on time can get counseling on extending repayment terms, installment repayment, and lower interest rates
Weekdays 09:00–18:00
Operated by · 신용회복위원회
Cost · Free
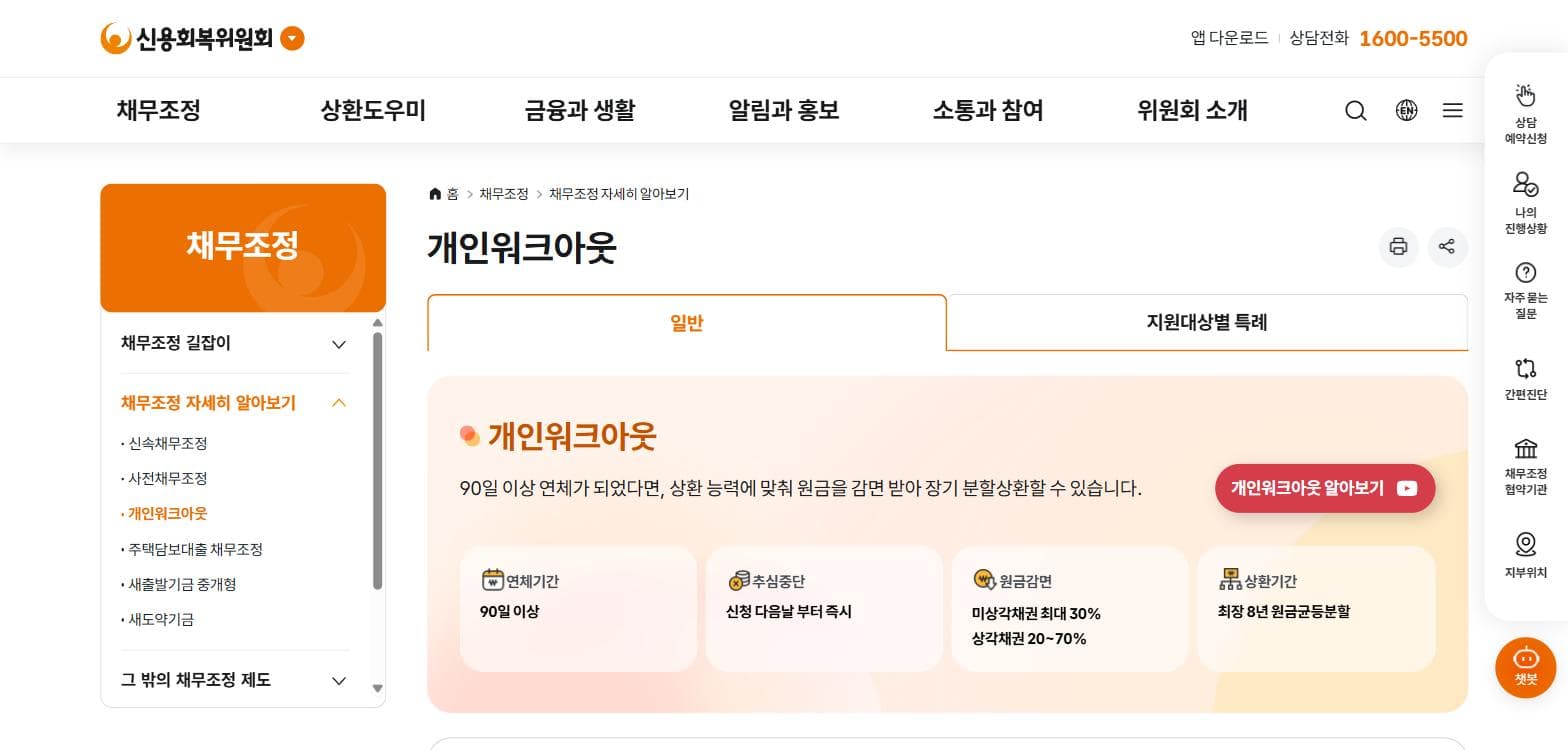
Credit Counseling and Recovery Service Individual Workout (Debt Adjustment)
A Credit Counseling and Recovery Service debt-adjustment program that adjusts the repayment period, interest, and principal for people with excessive debt
Weekdays 09:00-18:00 (counseling line 1600-5500)
Operated by · 신용회복위원회
Cost · Free
Regional Financial Welfare Center (Financial Welfare Call Center 1397)
A Korea Inclusive Finance Agency counseling channel where you can get Miso Finance/Sunshine Loan and debt-adjustment counseling in one place
Varies by center (call center 1397)
Operated by · 서민금융진흥원
Cost · Free
Korea Legal Aid Corporation Free Legal Counseling (132)
A public organization offering free legal counseling and litigation support for people facing financial hardship
Weekdays 09:00–18:00 (phone); online consultation accepted anytime
Operated by · 대한법률구조공단(법무부 산하)
Cost · Free